Inter Banking & Money Transfer
Banco Inter SAFinanceVerified
- 1.55K Reviews
- 4.4
- Downloads
- 100,000,000+
- Price
- Free
App Specs
- Version
- 26.15.1
- Updated
- Downloads
- 100,000,000+
- Requires
- 7.0
- Price
- Free
- Age Rating
- Everyone
Screenshots
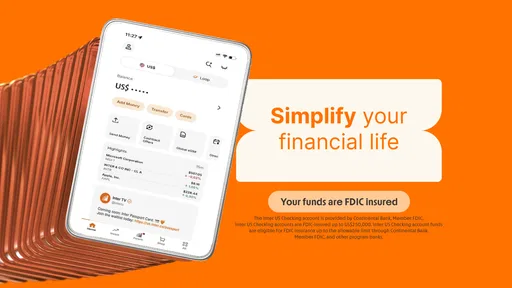
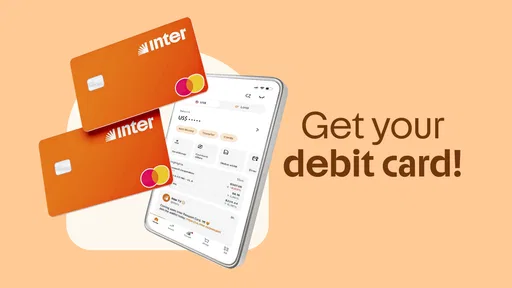
 Analysis by Appwesome
Inter Banking & Money Transfer is the kind of finance app I would recommend to someone who wants to bring everyday banking, shopping extras, and international transfers into one place rather than manage several separate services. My overall impression is positive: it feels designed for people who prefer handling money from a phone, but its broad scope also means that the experience is not equally compelling for every type of user. Its biggest strength is convenience, not specialization.
Developed by Banco Inter SA, this free finance app combines digital banking tools with gift cards and international money transfers. It is available to an Everyone audience, and its long presence in the mobile banking space gives it a more established feel than a newly launched wallet. The app was released on May 4, 2016, and the current Android version is 26.15.1, with Android 7.0 or later required.
The scale of its audience is also notable. It has passed 100 million installs and holds an average rating of 4.4 from around 4.9 million ratings. I would not treat those figures as proof that every banking task will work perfectly for every person, but they do show that this is a widely used product rather than a niche experiment. The developer’s name, Banco Inter SA, is visible enough to make the app’s banking identity clear from the start.
What using the app feels like in everyday banking
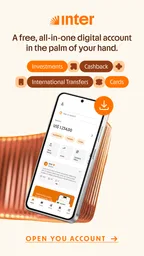
The most useful way to understand this app is to stop thinking of it as only a bank account interface. Its appeal comes from putting several money-related jobs close together. I can imagine opening it to deal with normal banking, then using the same environment for a gift card or an international transfer instead of switching between a traditional bank, a separate payment service, and a shopping platform.
That matters in ordinary situations. Imagine planning a trip while paying a household bill and buying a digital gift for a family member. With a conventional setup, those jobs may involve separate apps, different logins, and several places to check transaction details. Inter Banking & Money Transfer is more attractive when the goal is to reduce that fragmentation. The benefit is not that every individual tool will necessarily beat a specialist service; the benefit is that the overall routine can be simpler.
I also like the way the app’s range can support different stages of a financial task. A person might use the banking side for regular money management, move to the transfer function when dealing with someone abroad, and use the gift-card area for a purchase that does not need a physical item. That combination gives the app a practical identity beyond a basic account dashboard.
There is a trade-off, though. An all-in-one app can feel busier than a focused banking app. When financial information, shopping options, and transfer tools share the same product, the interface has more competing purposes. Users who only want to check a balance or make a simple payment may prefer a quieter application with fewer destinations to explore.
Other Stories to Read
All articles
 PUBG MOBILE
’s Lobby Demands Too Much Before the First Shot
A sharp, hands-on critique of how PUBG MOBILE guides players through its crowded lobby, high-pressure firefights, and the messy moments when a plan falls apart.
Read story: PUBG MOBILE’s Lobby Demands Too Much Before the First Shot
 Microsoft SwiftKey AI Keyboard
Should You Switch to SwiftKey? A Verdict for Every Kind of Typist
A case-by-case verdict on Microsoft’s keyboard: where its predictions, customization, and AI tools help, and where the trade-offs make a different choice wiser.
Read story: Should You Switch to SwiftKey? A Verdict for Every Kind of Typist


The strongest reason to choose it
For me, the strongest argument is the way it connects domestic banking habits with occasional international needs. Many people do not send money abroad every day, but when they do, they want the process to sit near the rest of their financial activity. Having that option inside a banking app can make it easier to start from a familiar account rather than researching a separate service at the last minute.
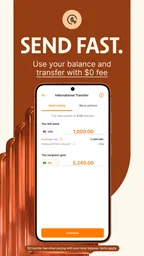
The same logic applies to gift cards. They are not a substitute for every kind of purchase, but they can be useful when I want to send something quickly or give someone the freedom to choose their own item. The app’s store summary highlights both gift cards and international money transfers, and those additions help distinguish it from a standard mobile banking tool.
A less obvious advantage is organizational. Keeping related actions in one app can make it easier to remember where a transaction happened. If I buy a gift card through one service, send money through another, and manage my account through a third, reviewing activity later becomes a small administrative task. A consolidated environment can reduce that mental overhead, especially for someone who prefers one main financial home.
That convenience becomes more valuable when the user has a mixed routine. Someone who receives money, pays for normal expenses, occasionally shops digitally, and sometimes deals with international transfers may get more from this app than someone who only wants a basic checking experience. The broader the routine, the more the all-in-one design starts to justify itself.
Where the experience needs patience
The main weakness is the same feature that makes the app attractive: its breadth. A banking application has to make financial actions feel clear and deliberate, while gift cards and transfer services introduce additional choices and expectations. I would not want a crowded home screen to make an important banking action harder to find, and users who value minimalism may feel that tension more strongly than I did.
International transfers also deserve a careful approach. I would check the recipient details, destination, currency, and final confirmation screens slowly rather than treating the process like a casual payment. Money sent across borders can involve more variables than a normal local transaction, so the convenience of having the feature in the app should not turn into rushed decision-making. The app is useful here, but the user still needs to review each step personally.
Gift cards have their own practical limitation: they are convenient only when the recipient and the purchase fit the card’s intended use. A digital gift is not automatically better than sending money or buying a physical item. I would use this function when I know the recipient will appreciate the choice, not simply because it is visible inside the app.
Another point is that a high rating does not eliminate the need to evaluate the app against personal banking priorities. A person may care most about a very specific service, a particular support style, or a specialized currency workflow. Inter Banking & Money Transfer can be a strong general-purpose option without being the best tool for every specialized requirement.
Small workflows that make a real difference
My first practical tip is to separate routine actions from occasional ones. I would use the central banking functions for regular money management and treat international transfers as a task that deserves a dedicated review before confirming. This simple habit prevents the broader app from encouraging a rushed, one-tap mindset when the transaction has more consequences.
My second tip is to use gift cards intentionally rather than impulsively. Before buying one, I would confirm that the recipient can use it for the intended purpose and that the value matches the occasion. The advantage of the feature is speed and convenience, but that advantage disappears if the card is unsuitable or less flexible than a direct transfer.
A third useful insight is that the app may be most valuable as a consolidation tool, not as a reason to abandon every other financial service immediately. I would start by identifying which tasks I genuinely want in one place. If the app handles those central needs comfortably, I could gradually rely on it more. This is safer and more realistic than moving an entire financial routine at once simply because an app offers many features.
I would also pay attention to how I personally navigate the interface over several sessions. A finance app can seem straightforward during a quick launch but feel different when I return to find a previous transaction, begin a transfer, or switch between banking and shopping-related areas. The right test is not whether the first screen looks attractive; it is whether I can locate important actions without hesitation.
Who will get the most from it?
I think the best audience is someone who wants a broad digital banking experience and values having extra money services nearby. It suits people who prefer managing finances from a smartphone, occasionally purchase gift cards, or need an international transfer option without maintaining a completely separate app for every job.
It may also work well for users who are tired of scattered financial routines. If I already use one app for banking, another for digital gifts, and another for sending money abroad, consolidating some of that activity could make daily life easier. The advantage is especially clear for people who are comfortable reviewing transactions digitally and do not need a branch-centered experience.
The Everyone age classification makes the app broadly accessible in terms of its listed content rating, but that should not be confused with financial simplicity. Younger or inexperienced users still need to understand what they are doing before sending money or buying a gift card. The app can provide the tools; it cannot replace careful judgment.
I would be more cautious about recommending it to someone who wants a highly specialized international-transfer service above everything else. A dedicated provider may offer a more focused workflow for that single purpose. Likewise, a user who wants an extremely stripped-down banking interface may find the additional shopping and transfer areas distracting rather than helpful.
How it compares with familiar alternatives
Compared with a traditional bank’s mobile app, Inter Banking & Money Transfer feels more ambitious because it places gift cards and international transfers beside ordinary digital banking. A conventional bank application may feel more narrowly centered on accounts and payments, which can be preferable when simplicity is the priority. Inter’s advantage appears when the user wants more activities in one ecosystem.
Compared with a standalone digital wallet, this app has a stronger banking identity through Banco Inter SA. A wallet can be excellent for quick payments or storing a limited amount of money, but it may not feel like a complete financial home. Inter Banking & Money Transfer is better suited to someone who wants banking and additional services connected rather than a single-purpose payment layer.
Compared with a specialist international-transfer app, its likely advantage is convenience inside a broader financial routine. The specialist may be the better choice for someone who sends money abroad frequently and wants every screen optimized around that task. Inter is more appealing when international transfers are important but not the only reason for installing the app.
Compared with buying gift cards directly from a retailer, the in-app route can be more convenient when I am already managing money there. The downside is that convenience should not be mistaken for universal value. A retailer’s own option may be more suitable when I need a particular brand, format, or purchase condition that the banking app does not match.
What I would check before relying on it
Before making Inter Banking & Money Transfer my main finance app, I would test the actions that matter most to me rather than judging it only by its feature list. I would look at how quickly I can reach everyday banking, how clearly transaction information is presented, and whether the transfer workflow feels understandable from recipient selection through final confirmation.
I would also decide whether the all-in-one structure helps or distracts me. If I regularly use gift cards and need international transfers, the extra sections are likely to feel useful. If I only check balances and make local payments, the broader design may offer little practical benefit over a simpler banking application.
Because this is a financial product, I would keep my device updated and use the app carefully, especially when handling recipients or reviewing a transfer. Those are sensible habits for any banking service, but they matter even more when one application combines several types of money activity. The free price removes a barrier to trying it, so a gradual test is more sensible than committing based only on its popularity.
The app’s version history will also matter to people who use older devices. The current version, 26.15.1, requires Android 7.0 or later, so anyone using an older Android release should check compatibility before planning around it. For supported devices, the broad install base suggests that it is intended for mainstream mobile use rather than a narrow technical audience.
My final recommendation
After looking at the complete experience, I see Inter Banking & Money Transfer as a capable choice for people who want banking, gift cards, and international money movement in one app. Its appeal is practical and easy to understand: fewer separate services, one familiar place to manage several financial needs, and a free entry point for trying the experience.
My recommendation comes with a clear condition. I would choose it for convenience and breadth, not because it must outperform every specialist alternative. Users who value a focused international-transfer workflow or a very minimal banking interface may be happier elsewhere. For everyone else, especially people with a mixed digital-finance routine, the combination is genuinely useful.
In my view, the app succeeds when it acts as a central financial workspace rather than trying to make every feature the only tool a person will ever need. I would install it, test the banking flow first, and then decide whether the gift-card and international-transfer functions fit my habits. If your priority is having more of your money routine together in one place, this is an app worth trying.
Highlights
- Fast transfers between supported banks and accounts.
- Convenient access to balances and transaction history.
- Useful for managing multiple banking services in one app.
- Transfer confirmations help users track completed payments.
- Available anytime without visiting a physical branch.
Limitations
- Features may vary depending on the user’s bank or region.
- Some transfers may include fees or processing delays.
- Requires a stable internet connection for most functions.
- Security checks can occasionally slow down urgent transfers.
- Customer support availability may be limited outside business hours.
Frequently Asked Questions
01What is Inter Banking & Money Transfer, and what can I use it for?
Inter Banking & Money Transfer is designed to help users manage banking-related activities and send money through a mobile device. Depending on the supported country, bank, and service provider, it may let you check balances, review transactions, transfer funds, and access payment features. Before downloading, confirm that the app supports your bank, currency, and destination country.
02Is Inter Banking & Money Transfer safe to use for financial transactions?
The app may include standard security measures such as account authentication, encrypted connections, transaction confirmations, and alerts. However, security also depends on your device, password habits, network connection, and the legitimacy of the downloaded application. Install it only from an official store, keep your operating system updated, and never share verification codes or banking credentials.
03Are there fees or limits when transferring money with the app?
Transfer costs and limits can vary according to the selected service, destination, currency, bank, and payment method. Some transactions may be free, while others can include service charges, exchange-rate markups, or receiving-bank fees. Review the final confirmation screen carefully before approving a transfer, especially for international payments or larger amounts.
04What information is required to send money through Inter Banking & Money Transfer?
You will generally need to create or verify an account and provide personal information required by financial regulations. A transfer may also require the recipient’s full name, bank or account details, phone number, email address, or other identification information. Enter every detail carefully, because incorrect information can delay the payment or make recovery difficult.
05What should I do if a transfer is delayed, rejected, or sent incorrectly?
First, check the transaction status, recipient details, balance, and any notification explaining the problem. Some transfers are delayed because of bank processing times, weekends, compliance checks, or currency conversion. If the information is incorrect or the payment remains unresolved, contact the app’s official support team and your bank promptly, keeping the transaction reference and confirmation details available.
Inter Banking & Money Transfer in other languages
